10 Best Car Loans for Bad Credit: Ranked and Compared
Bad credit can make buying a car feel harder than it should. Many lenders ask for strong credit scores, strict income proof, or large down payments. That is why many buyers start searching for the best car loans for bad credit when they need a fair path to financing.
That is why many buyers start searching for the best car loans for bad credit when they need a fair path to financing. These loans are aimed at people with limited credit history, past payment issues, or a low score. This review is for readers who want a car loan that fits a tighter credit profile.
It may help you compare rates, loan terms, approval rules, and extra fees without guessing. You will also see which features matter most before signing a loan agreement.
By the end, you should have a clearer idea of what each option offers and whether it suits your budget.
Here’s a catchy subtitle you can use before the comparison list: **Finding the right auto financing options when your credit isn’t perfect**
| Image | Product | Price |
|---|---|---|
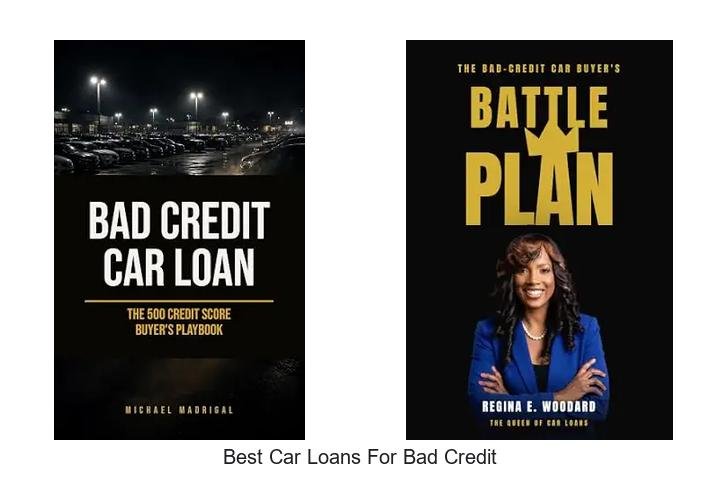
Pick 1  | Bad Credit Car Loan Buyer’s Playbook | Check Price On Amazon |
Pick 2  | The Bad-Credit Car Buyers Battle Plan | Check Price On Amazon |
Pick 3  | Mullen Wilder How Tos Loan Guide | Check Price On Amazon |
1. Bad Credit Car Loan Buyer’s Playbook
Credit repair advice can matter just as much as loan shopping. That is the main appeal here for buyers needing faster score help.
Bad Credit Car Loan: The 500 Credit Score Buyer’s Playbook is a short English guide focused on quick, practical credit-score improvement. Its 31-page length makes it easy to finish fast, and Word Wise support helps with reading difficult terms. Screen reader support and enabled enhanced typesetting also improve accessibility on supported devices.
The file is small at 913 KB, so it should download quickly and store easily. Page Flip support adds convenience for digital reading.
The guide suits readers who want a compact, low-friction resource before applying for auto financing with challenged credit.
Pros
- Very short and easy to finish quickly
- Word Wise helps explain tougher terms
- Screen reader support improves accessibility
Cons
- Very brief, so coverage may feel limited
- No printed edition details were provided
- Focuses narrowly on one credit situation
Who Should Buy It?
People with low credit scores who want fast, simple guidance should buy it. It also fits readers who prefer a short digital guide over a longer book. The accessibility features make it a sensible choice for users who rely on screen readers or Word Wise support.
Key Specifications
| Specification | Details |
|---|---|
| Title | Bad Credit Car Loan: The 500 Credit Score Buyer’s Playbook |
| Publisher | Learn more |
| Publication Date | September 30, 2026 |
| Language | English |
| Print Length | 31 pages |
| File Size | 913 KB |
| Accessibility | Screen Reader Supported |
| Enhanced Typesetting | Enabled |
| Word Wise | Enabled |
The title signals a guide aimed at buyers with a 500 credit score. A 31-page length means the reading load stays light and quick. The English language setting suits straightforward reading, while the 913 KB file size suggests fast downloading and easy storage. Accessibility support matters here, since screen readers can access the content. Word Wise may help with unfamiliar terms, which can make the book easier to follow for newer readers.
Enhanced typesetting and page flip support improve digital reading comfort on supported devices. Those features can make short sessions easier, especially for readers who prefer mobile or tablet use. The compact file size also helps people who want a quick reference guide without much device space used. Since the book is brief, readers seeking broad coverage may want more material. Buyers who value simple access and easy reading will benefit most.
2. The Bad-Credit Car Buyers Battle Plan
Bad credit can turn a car purchase into a pressure test. This field guide focuses on dealer trick defense and money protection.
The book presents a step-by-step approach for buyers in Michigan and beyond. It covers getting approved, spotting dealer tactics, and protecting cash. At 102 pages, it stays compact and practical rather than overly long.
The independently published format suggests a focused, niche guide for everyday buyers. Its English language presentation makes it accessible for straightforward reading.
The 6 x 0.23 x 9 inch size also suggests an easy-to-handle paperback. Readers who want a plain, tactical guide may value that simplicity. Buyers facing credit challenges may like its direct focus on approval and negotiation.
It suits people who want a clearer plan before entering a dealership.
Pros
- Focuses on dealer-trick defense.
- Covers approval and money protection.
- Compact format is easy to read.
Cons
- Limited to 102 pages.
- Narrow focus may not suit all buyers.
- No digital format details are provided.
Who Should Buy It?
People with bad credit who want a practical dealership strategy should consider it. It suits buyers who want approval guidance and fraud awareness in one short guide. Michigan readers may find the regional reference helpful, while others can still use the broader advice.
It works best for careful shoppers who want a simple, readable plan before visiting a dealer.
Key Specifications
| Specification | Details |
|---|---|
| Title | The Bad-Credit Car Buyer’s Battle Plan: A Step-by-Step Field Guide to Getting Approved, Dodging Dealer Tricks, and Protecting Your Money in Michigan and Beyond |
| Publisher | Independently published |
| Publication Date | October 3, 2026 |
| Language | English |
| Print Length | 102 pages |
| File Size | Not provided |
| Accessibility | Not provided |
| Enhanced Typesetting | Not provided |
| Word Wise | Not provided |
The 102-page length suggests a short, focused guide for quick reading. Its 6 x 0.23 x 9 inch dimensions point to a slim paperback format. That size usually feels easy to carry and store in a bag. English language text makes it straightforward for many readers. The independently published label indicates a niche title with a specific audience. Buyers who want a compact manual rather than a long reference may appreciate that format.
A shorter print length can make the material easier to finish before visiting a dealer. The slim build may also make it convenient to keep nearby during shopping. Since no digital features are listed, buyers should rely on the print edition details. The publication date is October 3, 2026, which places it in a recent release window. That may appeal to readers seeking current guidance. People who want concise, direct advice may benefit most from these specs.
3. Mullen Wilder How Tos Loan Guide
Bad credit borrowers often need clear steps, not vague advice. Mullen Wilder’s guide focuses on that practical need with a simple how-to format.
The book explains how to get a loan with bad credit in 2025. It is part of the Mullen Wilder’s “How To’s” series. The English edition was published on February 18, 2025.
Its 549 KB file size suggests a lightweight digital read. Screen reader support and enhanced typesetting improve access and reading comfort.
Word Wise and page flip also help make the material easier to use. The guide suits readers who want structured loan help in plain language. It may appeal most to people who prefer a short, digital reference.
The format feels efficient for quick consultation during loan research. That makes it a practical fit for busy borrowers who want direction.
Pros
- Step-by-step approach suits first-time borrowers.
- Screen reader support improves accessibility.
- Lightweight file loads quickly on devices.
Cons
- No print length listed.
- Not ideal for readers wanting extensive detail.
- Single-guide format may feel limited.
Who Should Buy It?
People who want straightforward loan guidance should consider it. It suits readers with bad credit who need a simple process. The digital format fits anyone who prefers quick reference material.
Screen reader support also helps users who need accessible reading options. It works best for borrowers who value clear, step-by-step direction over long explanations.
Key Specifications
| Specification | Details |
|---|---|
| Title | How to Get a Loan with Bad Credit in 2025 (Mullen Wilder’s “How To’s”) |
| Publisher | Mullen Wilder |
| Publication Date | February 18, 2025 |
| Language | English |
| File Size | 549 KB |
| Accessibility | Learn more |
| Enhanced Typesetting | Enabled |
| Word Wise | Enabled |
The title tells readers exactly what the guide covers. It focuses on getting a loan with bad credit in 2025. That makes the purpose clear before opening the file. The English language setting helps readers who want an easy read. A 549 KB file size usually means fast downloads and light storage use. Screen reader support also points to wider accessibility for digital reading on phones, tablets, or assistive devices.
Enhanced typesetting can improve spacing and layout on supported screens. Word Wise can help readers handle unfamiliar words with less effort. Page flip support offers a more book-like reading flow on digital devices. These features make the guide easier to use in short sessions. They suit borrowers who want quick access to steps and definitions. Since the file is compact, it should be convenient for frequent reference.
4. Business Credit Bible for Beginners

Starting a business credit journey can feel confusing at first. A step-by-step guide helps break the process into manageable actions.
Business Credit Bible for Beginners focuses on helping readers build business credit, seek loans, and understand tradelines. It is written for beginners and people with bad credit or limited starting knowledge. The book is independently published and runs 128 pages, so it stays compact and approachable.
Its small 6 x 0.29 x 9 inch format should make it easy to carry and read anywhere. The plain presentation suits readers who want direct guidance without extra filler. Because it centers on business credit, it fits buyers who want a practical starting point for funding-related planning.
It may appeal most to people forming a business identity and learning the basics. The shorter length may also suit readers who want a focused guide instead of a long manual.
Pros
- Focuses on business credit loans and related funding tools.
- Written for beginners with limited credit knowledge.
- Compact 128-page format makes it easy to read.
Cons
- Not a car-loan specific guide.
- No digital file details were provided.
- Printed length may feel brief for advanced readers.
Who Should Buy It?
People starting a business credit journey may find this guide useful. It suits beginners who want a simple overview of loans, credit cards, and tradelines. Readers with bad credit or little experience may appreciate the step-by-step approach.
It also fits anyone who prefers a short, focused paperback on business funding basics.
Key Specifications
| Specification | Details |
|---|---|
| Title | Business Credit Bible for Beginners: The Step-by-Step System to Get Loans, Credit Cards and Tradelines – Even If You Have Bad Credit or No Idea Where To Start |
| Publisher | Independently published |
| Publication Date | May 27, 2025 |
| Language | English |
| Print Length | 128 pages |
The title shows a beginner-focused guide on business credit basics. It mentions loans, credit cards, and tradelines, which points to a broad funding roadmap. The 128-page length suggests a concise read rather than a heavy reference book. Independent publishing often means the author controls the teaching style and pacing. For everyday use, that can mean direct language and a simple layout. Readers who want a short starting point may appreciate that format.
The publication date is May 27, 2025, so the book is recent. An English-language edition makes it accessible to many readers in the United States. The compact 6 x 0.29 x 9 inch size also suggests easy handling and storage. The listed item weight of 8.8 ounces points to a lightweight paperback. That can help readers carry it to work, meetings, or study sessions. New business owners may benefit most from its portable, focused design.
5. Car Loan Payments Log Book

Staying organized can make auto payments feel far less stressful. A simple written log helps you track what went toward principal, interest, and balances.
Car Loan Payments Log Book offers a focused way to record monthly auto loan details. It includes space for payment tracking across 100 pages, all in a compact 6 by 9 inch format.
The book is published independently and printed in English, with a 102-page length that keeps the layout practical and easy to carry. Its purpose is straightforward, giving drivers a dedicated place to monitor loan progress without relying on scattered notes.
The format suits people who prefer handwritten records and want clearer visibility into payment history. Build quality appears suited to everyday use, with a portable size that fits a glove box, desk drawer, or bag.
The layout should work well for anyone who wants a simple paper organizer for car loan management. It offers solid value for buyers who want a focused payment tracker rather than a complex finance tool.
Pros
- Tracks principal, interest, and balances clearly
- Compact size fits easily in storage spaces
- Simple format supports handwritten record keeping
Cons
- No digital features or syncing options
- Limited to manual tracking only
- Not suited for users wanting automation
Who Should Buy It?
People who prefer handwritten finance records should consider it. It suits drivers managing auto loans who want a dedicated place for monthly payment details. The compact format also works well for anyone keeping loan notes at home, in a car, or in a work bag.
Buyers who want a simple, paper-based organizer will get the most use from it.
Key Specifications
| Specification | Details |
|---|---|
| Title | Car Loan Payments Log Book: Track Monthly Payment, Principal, Interest, and Balances with Ease – Perfect Financial Organizer for Auto Loans. 100 Pages, 6″x9″ Inch. |
| Publisher | Independently published |
| Publication Date | January 25, 2025 |
| Language | English |
| Print Length | 102 pages |
The title shows exactly what the log book is meant to record. It tracks monthly payments, principal, interest, and balances in one place. That makes daily use straightforward for anyone who wants a written record of car loan progress. The 6 by 9 inch size suggests a compact book that fits easily into a small storage spot. A 100-page log layout gives room for repeated entries without feeling bulky.
An independently published book often means a focused format without extra filler. The English language setting makes the pages easy to use for most readers in that market. With 102 printed pages, the book offers enough space for ongoing payment records and related notes. The portable dimensions and light weight support regular handling, whether stored at home or carried with paperwork. It suits buyers who want a simple manual organizer for auto loan tracking.
6. The Weekend Car Flipper

Turning spare weekends into profit sounds appealing, and this guide explains one clear path. It focuses on buying, fixing, and selling used cars through a legal no-lot method.
The book targets readers with bad credit or little mechanic experience, which broadens its appeal. At 197 pages, it offers a focused format that should stay practical rather than padded. Enhanced typesetting and Word Wise support easier reading on compatible devices.
The file size is modest, so downloading and storing it should be simple. Screen reader support also makes it accessible to more readers.
As a learning guide, its value rests on the strategy rather than technical depth. That suits readers who want a direct plan without heavy jargon.
It may fit people exploring car flipping as a side business. The subject matter feels specific, which can help readers stay focused.
Pros
- Targets readers with bad credit or limited experience.
- Explains a legal no-lot car flipping method.
- Compact length supports focused reading.
Cons
- Not a loan product or financing guide.
- No mechanic-level detail is listed.
- Publication date is in the future.
Who Should Buy It?
People interested in car flipping should consider this guide. It suits readers who want a legal buying and selling method. The book may appeal to beginners with bad credit.
It also fits anyone with little mechanic experience. Readers wanting a short, practical overview may benefit most. Those seeking direct side-income ideas may find it useful.
Key Specifications
| Specification | Details |
|---|---|
| Title | THE WEEKEND CAR FLIPPER: How to Buy, Fix, and Sell Used Cars for Consistent Profit Using the ‘No-Lot’ Legal Method (Even With Bad Credit or No Mechanic Experience) |
| Publisher | Not listed |
| Publication Date | November 10, 2026 |
| Language | English |
| Print Length | 197 pages |
| File Size | 2.9 MB |
| Accessibility | Screen Reader Supported |
| Enhanced Typesetting | Enabled |
| Word Wise | Enabled |
The title shows a clear focus on used-car flipping and profit. It also signals that the method stays legal and no-lot based. The listed print length of 197 pages suggests a concise read. A 2.9 MB file size usually means easy downloading and storage. Screen reader support helps readers using accessibility tools. Word Wise can make difficult passages easier to follow. Enhanced typesetting also improves how text appears on supported devices.
These specs point toward a lightweight digital guide for focused study. The shorter length may suit readers who want practical reading time. The English language listing broadens access for common readers. Page Flip can help people move through sections quickly. Screen reader support and Word Wise make the book friendlier for beginners. Enhanced typesetting should improve readability on phones or tablets. The future publication date means availability may depend on release timing.
7. Bad Credit No Problem Metal Sign

Office walls get instant personality with this vintage-style metal sign. The bold slogan gives a clear, humorous message for finance-themed spaces.
Built from aluminum, it offers water resistance and rust protection for long-lasting display. The distressed black background, worn border, and bright lettering create a classic storefront look.
UV printing helps the colors stay vivid and easy to read indoors or outdoors. Its 8 x 12 inch size fits well without crowding a wall. Four pre-drilled holes make hanging simple with screws, hooks, or rope.
Slight bends from shipping can be pressed back by hand. It suits loan offices, car dealerships, storefronts, pawn shops, and home workspaces. The lightweight build also makes it easy to move and reposition.
For business owners wanting decor with a playful edge, it offers solid value.
Pros
- Lightweight aluminum resists rust and water
- UV printing keeps wording clear and bright
- Easy to hang with four pre-drilled holes
Cons
- Decorative only, not a functional loan sign
- Small size may not suit large walls
- Vintage style may not fit modern offices
Who Should Buy It?
Buyers who want a finance-themed office accent will appreciate it most. It suits loan brokers, car dealership offices, storefronts, and pawn shops. Business owners who like vintage wall decor can use it as a conversation piece.
It also works as a gift for entrepreneurs, housewarmings, birthdays, or opening celebrations.
Key Specifications
| Specification | Details |
|---|---|
| Title | Bad Credit No Problem Metal Sign 8 x 12 Inch |
| Language | English |
| Print Length | Single sign plaque |
| File Size | Not applicable |
| Accessibility | Not provided |
| Enhanced Typesetting | Not provided |
| Word Wise | Not provided |
| Publisher | LIPENK |
| Publication Date | Not provided |
The 8 x 12 inch size gives the sign a clear presence without overwhelming a wall. Aluminum construction keeps it light at 3.85 ounces, so handling stays simple. The rectangular shape and wall-mount design fit office spaces, storefronts, and work areas. Four pre-drilled holes help with fast hanging using screws, hooks, or rope. The multicolor printed surface adds visual contrast, while the black background and rusted border create a vintage look that is easy to place indoors or outdoors.
These specifications make setup easy for business owners and gift buyers alike. The lightweight metal body is less likely to stress mounting points, and small bends can be pressed back by hand. Water resistance and rust protection help it suit covered outdoor spots, while UV printing supports readable text over time. The compact size works best for smaller walls, reception areas, or desk-side displays. It fits users who want simple installation and low-maintenance decorative signage.
8. Car Loan Payments Log Book

Tracking a car loan can feel messy fast. A simple paper log helps keep every payment clear and organized.
Car Loan Payments Log Book focuses on monthly auto finance records. It gives space for principal, interest, and balance tracking. The 100-page interior suits borrowers who want steady payment records.
Its compact 6 x 9 inch size makes it easy to store. The book is lightweight enough for a glove box or desk drawer. Because it is independently published, it keeps the format straightforward.
The layout suits people who prefer handwriting over apps and spreadsheets. That can help when you want a quick record during a payment call. It also works well for anyone rebuilding credit with careful habits.
The book is simple, practical, and centered on loan tracking alone.
Pros
- Dedicated pages for auto payment tracking
- Records principal, interest, and balances
- Compact size fits easy storage
Cons
- Paper format lacks digital search
- No built-in reminder features
- Limited to manual entry only
Who Should Buy It?
Who should buy it: Drivers who want a simple paper record for loan payments may like this log book. It suits people who track principal, interest, and balances by hand. Borrowers managing auto finance after credit setbacks may also appreciate the clear monthly format.
Anyone who prefers writing notes over using apps will find it practical.
Key Specifications
| Specification | Details |
|---|---|
| Title | Car Loan Payments Log Book: Monthly Auto Finance Tracker for Recording Principal, Interest, and Balances |
| Publisher | Independently published |
| Publication Date | July 21, 2025 |
| Language | English |
| Print Length | 100 pages |
The title shows exactly what the book tracks each month. It is built for recording principal, interest, and balances in one place. That format helps drivers keep payment details together instead of scattered across receipts. The 100-page print length gives room for regular monthly entries. English language text also makes the pages straightforward to read and fill out. These details point to a simple tool for personal loan records.
The compact 6 x 9 inch format works well for storage and handling. Its 7.2-ounce weight makes it easy to carry between home and car. A 0.23-inch thickness keeps it slim inside a bag or drawer. Because it is independently published, the setup stays direct and uncluttered. That suits buyers who want a lightweight log for steady use. It fits people who value manual recordkeeping over app-based tracking.
9. How to Be Debt Free

Debt payoff can feel messy when car loans, cards, and student debt overlap. A small guide can make the next payment feel more manageable.
How to Be Debt Free offers a simple plan for paying off debt across several common loan types. It covers car loans, student loan repayment, credit card debt, mortgages, and more.
The book is part of the Smart Money Blueprint series and runs 110 pages. That length suggests a focused read rather than a long financial manual.
The 1st edition was published by CreateSpace Independent Publishing Platform in English. Its compact size may suit readers who want a light, easy-to-hold reference.
The topic fits borrowers who need structure after taking on a car loan with bad credit. It appears aimed at people who want clear repayment steps without heavy jargon.
The format feels approachable for quick reading and repeated review. Anyone seeking a practical starting point for debt payoff planning may find it useful.
Pros
- Covers multiple debt types in one short guide.
- Compact format is easy to read and revisit.
- Simple plan may suit new budget planners.
Cons
- Short length may feel limited for advanced readers.
- No detailed data about exercises or tools.
- Less suited to readers wanting a large reference.
Who Should Buy It?
People with car debt and other balances may benefit most. It suits readers who want a short, simple repayment guide. Buyers who prefer a compact book over a dense finance manual may like it.
It may also help anyone starting a basic debt payoff plan after credit trouble.
Key Specifications
| Specification | Details |
|---|---|
| Title | How to Be Debt Free: A simple plan for paying off debt: car loans, student loan repayment, credit card debt, mortgages, and more. Debt-free living is … Finance Books) (Smart Money Blueprint) |
| Publisher | CreateSpace Independent Publishing Platform |
| Publication Date | November 15, 2016 |
| Language | English |
| Print Length | 110 pages |
The 110-page print length points to a concise guide that reads quickly. A shorter book often works well for people who want direct repayment ideas. The English language edition makes it easy for many readers to follow. Since the publisher is CreateSpace Independent Publishing Platform, the book comes from a self-publishing platform. That setup often suits straightforward personal finance guides. Readers who want a compact overview may appreciate the lighter format and easy handling.
The November 15, 2016 publication date places it within a modern budgeting period. A small 6 x 0.25 x 9 inch size suggests simple shelf storage and easy carrying. The 5.6 ounce weight also makes it light to hold or pack. As a first edition, it offers the original version from the series. People who like short, physical books may benefit most. Those wanting quick reading sessions may find the format practical for regular review.
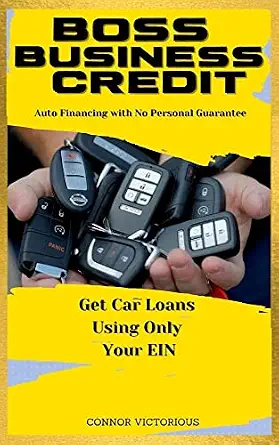
10. BOSS BUSINESS CREDIT Auto Financing
Business borrowers get a clear path to vehicle financing here. The focus on EIN-only applications makes it stand out quickly.
BOSS BUSINESS CREDIT Auto Financing centers on getting car loans using only an EIN, without a personal guarantee. That setup may appeal to owners who prefer separating business and personal borrowing.
The listing is a short, 16-page publication in English, with Word Wise and page flip support. It also supports screen readers and enhanced typesetting, which can help with accessibility and reading flow.
The file is small, so it should be quick to download and easy to open on most devices. Its compact length suggests a focused guide rather than a lengthy manual.
That can suit readers who want a concise starting point before pursuing business auto financing options. The format feels simple, direct, and easy to digest for busy owners.
It may suit entrepreneurs who need a brief overview of EIN-based auto finance. It is also a practical fit for readers who want a lightweight digital guide.
Pros
- Focuses on EIN-only auto financing
- No personal guarantee is highlighted
- Short, easy-to-read digital format
Cons
- Very brief at 16 pages
- Limited detail compared with longer guides
- Not suited for readers wanting broad loan coverage
Who Should Buy It?
Business owners who want vehicle financing tied to an EIN may value this guide. It suits readers seeking a short, focused overview instead of a long manual. The no personal guarantee angle may appeal to people separating business borrowing from personal credit.
It fits entrepreneurs who prefer concise digital reading and accessible formatting support.
Key Specifications
| Specification | Details |
|---|---|
| Title | BOSS BUSINESS CREDIT: Auto Financing with No Personal Guarantee: Get Car Loans Using Only Your EIN |
| Publisher | Learn more |
| Publication Date | January 2, 2023 |
| Language | English |
| Print Length | 16 pages |
| File Size | 123 KB |
| Accessibility | Screen Reader Supported |
| Enhanced Typesetting | Enabled |
| Word Wise | Enabled |
The title signals a focus on auto financing through an EIN alone. That means the guide centers on business-oriented borrowing, not a broad consumer loan handbook. The January 2, 2023 publication date shows it is a recent digital resource. English language support makes it straightforward for many readers. A 16-page length suggests a compact read, which suits busy owners. The 123 KB file size points to a lightweight download and fast access.
Screen reader support helps readers who rely on accessibility tools. Enhanced typesetting can improve on-screen readability and layout clarity. Word Wise may help readers move through unfamiliar terms with less friction. These features make the guide easier to use on phones, tablets, and e-readers. The short format also keeps setup simple for readers who want quick guidance. People seeking a concise, accessible business auto finance overview may benefit most from these specs.
Best Car Loans for Bad Credit: A Smart Buyer’s Guide to Finding the Right Lender
Eligibility requirements
A lender’s approval process often depends on a borrower’s overall financial profile, and clear eligibility standards can make the difference between a smooth application and a rejected one. Minimum credit score expectations help determine which loan programs a lender may offer, while income and employment verification show whether monthly payments are realistic within the applicant’s budget. Residency and identification requirements are equally important because they confirm stability, identity, and compliance with lending rules.
Residency and identification requirements are equally important because they confirm stability, identity, and compliance with lending rules. Reviewing these conditions in advance can save time, reduce application errors, and make it easier to compare offers that match your current situation.
Interest rates and loan terms
APR for borrowers with poor credit is often higher than standard offers, so the loan structure can have a major impact on total repayment costs over time. Loan term length matters because a short-term option usually reduces the interest paid overall but can raise monthly installments, while a long-term option lowers the monthly amount at the expense of paying more interest across the full schedule. Rate type also deserves close attention: a fixed rate keeps payments predictable from start to finish, whereas a variable rate may begin lower but can rise later and increase the total cost unexpectedly.
Rate transparency and term flexibility should both be reviewed carefully, since they affect affordability, budgeting stability, and how much room you have to adjust the loan if your financial situation changes.
Fees and total borrowing cost
Origination fees, prepayment penalties, and late payment or dealer add-on charges can change the true cost of an auto loan far beyond the advertised interest rate. A low monthly payment may still become expensive if the lender adds upfront processing fees or charges extra for optional products at the dealership. It is also important to check whether paying the loan off early triggers a penalty, since that can limit your flexibility if your finances improve.
Review every fee in the loan terms and compare the full borrowing cost, not just the headline rate, so the agreement stays affordable from start to finish.
- Origination fees: Added at the start of the loan and may reduce the amount you actually receive.
- Prepayment penalties: Extra costs for paying off the balance ahead of schedule.
- Late payment and dealer add-on fees: Charges that can increase the total if payments are missed or optional extras are included.
Down payment and tradein options
A larger down payment can directly lower the amount financed, which may improve approval odds and reduce monthly costs. Minimum down payment expectations vary by lender, but borrowers with weaker credit often benefit from contributing more upfront because it signals commitment and lowers risk.
In many cases, combining a trade-in with extra cash up front can shrink the loan balance enough to make terms more manageable and interest charges less burdensome.
- Minimum down payment: A higher upfront amount can make the deal more acceptable to lenders.
- Trade-in value: Positive equity may improve approval chances by reducing the financed total.
- Upfront cash: Extra funds lower the loan amount and can lead to easier repayment.
Lender reputation and loan features
Lender reputation and loan features matter because a borrower’s experience often depends as much on service quality as on the interest rate itself. Reviews and customer service ratings can reveal how a lender handles real-world problems, such as unclear terms, delayed responses, or billing issues, which is especially important for applicants who may need extra guidance. An easy online application can save time and reduce stress, while fast funding may be helpful if the loan is needed quickly for an urgent vehicle purchase or refinancing need. Payment flexibility and hardship options also deserve attention, since life can change after the loan is approved; features such as due-date changes, deferment, or temporary relief can make repayment far more manageable during tight months.
Together, these details show whether a lender offers not just financing, but dependable support throughout the full loan term.
Affordability and ownership costs
Affordability and ownership costs can determine whether a vehicle remains manageable long after the paperwork is complete. A monthly payment that fits comfortably within your budget helps prevent financial strain, but the total cost of ownership also matters just as much.
Financed vehicles often come with insurance requirements that are higher than those for paid-off cars, so it is important to account for full coverage premiums before committing. Regular maintenance, unexpected repairs, and annual registration fees can also add up quickly, especially if the vehicle is older or has higher mileage. Factoring in these ongoing expenses from the start creates a clearer picture of the real financial commitment and helps avoid surprises later.
- Monthly payment: Keep it at a level that leaves room for other essential expenses.
- Insurance: Verify lender-required coverage and compare premium estimates in advance.
- Maintenance and repairs: Plan for routine service and possible unexpected fixes.
- Registration: Include yearly fees in the overall cost estimate.
How Bad-credit Car Loans Usually Work
Bad-credit car loans work much like standard auto loans, but lenders may review your credit history more closely. A lower score can mean a higher interest rate, a larger down payment, or a shorter loan term. Some lenders also ask for proof of steady income, residence, and insurance before approval.
These loans can be a useful way to buy a car when your credit score is not strong enough for regular financing. The main tradeoff is cost. A higher rate can make the vehicle more expensive over time, so it helps to compare more than one offer before choosing a lender.
Many buyers focus only on the monthly payment, but the full loan amount matters too. A longer term can lower the payment, yet it may also increase total interest paid. A shorter term may cost less overall, but the monthly bill can be higher.
Here are a few signs a loan may be a better fit:
- The monthly payment fits your budget with room left for gas, insurance, and repairs.
- The interest rate and fees are clearly listed.
- The lender reports payments to the credit bureaus.
- There is no large prepayment penalty if you pay it off early.
You may want to replace an old bad-credit loan later with a new one if your credit improves. Refinancing can sometimes lower the rate or shorten the term. It can also make sense if your income rises and you can handle a better payment plan.
Before signing, read the full agreement and ask questions about fees, payment dates, and late charges. A clear loan is easier to manage and can help you move toward better credit over time.
FAQ’s
What Are The Best Car Loan Options For Borrowers With Bad Credit?
The best car loan options for borrowers with bad credit are typically subprime auto loans, credit union loans, and buy-here-pay-here financing. It’s also smart to compare rates from multiple lenders and consider making a larger down payment to improve approval odds and lower costs.
How Can I Qualify For A Car Loan If I Have Bad Credit?
You can improve your chances by making a larger down payment, showing steady income, and applying with a co-signer or lender that specializes in bad credit auto loans. It also helps to check your credit report for errors and pay down existing debts before you apply.
What Interest Rates Should I Expect On A Bad Credit Car Loan?
Bad credit car loans usually come with higher interest rates, often ranging from about 10% to 20% or more depending on your credit score, income, and the lender. Your exact rate will also depend on the loan term, down payment, and the car you choose.
Are There Lenders That Specialize In Car Loans For Bad Credit?
Yes, many lenders specialize in car loans for bad credit, including some credit unions, online lenders, and dealerships. These lenders may offer higher interest rates or require a larger down payment to reduce their risk.
What Steps Can I Take To Improve My Chances Of Getting Approved For A Car Loan With Bad Credit?
To improve your chances, check your credit report for errors, pay down existing debt, and save for a larger down payment. You can also boost approval odds by applying with a co-signer, choosing a less expensive car, and getting preapproved by multiple lenders.
Final Verdict
For buyers comparing the best car loans for bad credit, Bad Credit Car Loan Buyer’s Playbook is the strongest overall choice because it focuses on quick credit-score help and practical next steps. BOSS BUSINESS CREDIT Auto Financing fits shoppers who want EIN-only auto finance and a value-friendly route tied to business credit. Business Credit Bible for Beginners is the premium pick for buyers building business credit loans and willing to pay more for a broader learning path.
The Bad-Credit Car Buyers Battle Plan is the best fit for anyone who wants dealer-trick defense and a sharper loan strategy before signing. Taken together, these picks match different needs: fast score help, EIN-based financing, business-credit growth, or negotiation protection.
Choose the guide that matches your main goal: score repair, EIN-only financing, business-credit building, or dealer defense.